
How to Create a Zero-Based Budget That Actually Works
Introduction
Traditional budgeting often fails because it’s built on yesterday’s spending patterns. Zero-based budgeting (ZBB) takes a different approach: every dollar gets a job before you spend it. Instead of adjusting last month’s budget, you start from zero and justify every expense. More From Mobelwealth: Best Budget Apps for Couples in 2025
After helping dozens of clients implement zero-based budgets over the past five years, I’ve seen this method transform financial lives. The Federal Reserve’s 2023 Survey of Consumer Finances revealed that 40% of Americans would struggle to cover a $400 emergency expense. Zero-based budgeting directly addresses this problem by ensuring intentional allocation of every dollar earned.
What Makes Zero-Based Budgeting Different
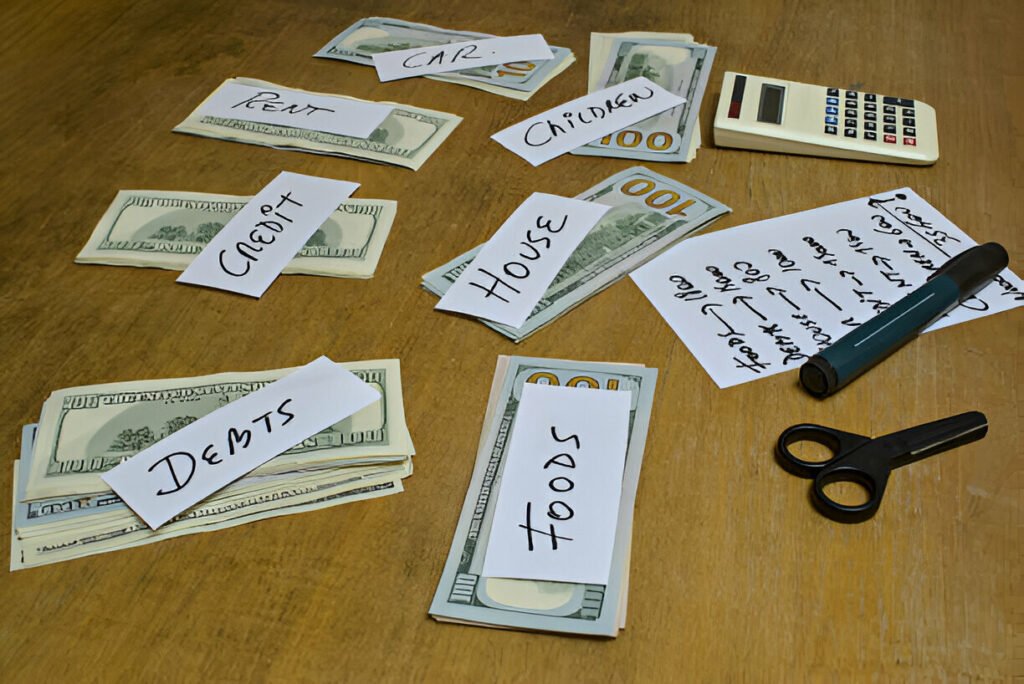
Zero-based budgeting originated in the corporate world during the 1970s when Peter Pyhrr developed it for Texas Instruments. The concept is simple: assign every dollar of income to a specific category before the month begins. Your income minus your planned expenses should equal zero.
This differs fundamentally from traditional budgeting methods. With percentage-based budgets like the 50/30/20 rule, you allocate fixed percentages to broad categories. Zero-based budgeting forces you to examine each expense individually and decide if it deserves space in your financial plan.
The psychological impact cannot be overstated. When you give every dollar a purpose, you eliminate the mental category of “leftover money” that often disappears without a trace. According to research from the Journal of Consumer Psychology, people who use detailed budgets spend 15% less on discretionary items compared to those using general spending guidelines. More From Mobelwealth: How to Budget Money: A Guide for Beginners
The Step-by-Step Process
Step 1: Calculate Your Monthly Income
Start with your after-tax income. If you’re paid bi-weekly, multiply your paycheck by 26 and divide by 12 to get your monthly average. For irregular income, use the lowest month from the past six months as your baseline.
Include only guaranteed income sources. Don’t factor in potential overtime, bonuses, or side hustle income until it becomes consistent. The Consumer Financial Protection Bureau recommends this conservative approach to avoid overspending based on optimistic projections. More From Mobelwealth: Master Your Finances: How to Use Our Budget Planner Tool Effectively
Step 2: List All Fixed Expenses
Fixed expenses remain constant each month. These typically include:
- Rent or mortgage payments
- Insurance premiums
- Loan payments
- Subscription services
- Utilities (use average amounts)
The Bureau of Labor Statistics’ 2024 Consumer Expenditure Survey shows that housing costs average 33% of after-tax income for American households. If your housing costs exceed 35%, zero-based budgeting becomes even more critical for managing remaining expenses.
Step 3: Identify Variable Expenses
Variable expenses change monthly but are necessary for daily life:
- Groceries
- Transportation costs
- Personal care items
- Clothing
- Entertainment
For variable expenses, review three months of bank statements to establish realistic averages. The USDA’s 2024 food cost reports indicate that a family of four on a moderate plan spends approximately $1,200 monthly on groceries. Use such benchmarks to validate your estimates.
Step 4: Assign Every Dollar
This is where zero-based budgeting gets its name. Subtract all expenses from your income. The remainder must be allocated to specific goals:
- Emergency fund building
- Debt payments beyond minimums
- Retirement contributions
- Savings goals
If you have money left over, resist the urge to leave it unassigned. Even $50 should have a specific purpose, whether it’s building your emergency fund or saving for a vacation.
Step 5: Track and Adjust Daily
Zero-based budgeting requires active management. Use a budgeting app or spreadsheet to track spending against your plan. When you overspend in one category, you must reduce spending in another to maintain the zero balance.
Common Pitfalls and How to Avoid Them
The Perfectionism Trap
New zero-based budgeters often abandon the system after one imperfect month. According to Research from the American Psychological Association shows that perfectionist tendencies in financial planning lead to higher rates of budget abandonment within 90 days.
Instead of aiming for perfection, focus on improvement. If you’re 85% accurate in your first month, that’s significantly better than having no budget at all. The National Foundation for Credit Counseling found that people who stick with budgeting for three months are 70% more likely to continue long-term.
Underestimating Irregular Expenses
Many budgeters forget about quarterly, semi-annual, or annual expenses like car registration, holiday gifts, or home maintenance. These irregular expenses derail budgets when they appear unexpectedly.
Create a separate category for irregular expenses and contribute to it monthly. If you spend $1,200 annually on car maintenance, budget $100 monthly for this category. This approach transforms unpredictable expenses into manageable monthly line items.
The Social Pressure Problem
Zero-based budgeting can feel restrictive when friends suggest expensive activities. The Federal Reserve Bank of St. Louis published research in 2023 showing that social spending pressure contributes to 23% of budget failures among adults under 35.
Plan for social activities by including them in your budget. If your entertainment budget is $150 monthly, you can confidently participate in activities within that limit while declining those that exceed it.
Advanced Strategies That Work
The Buffer System
Even with careful planning, life happens. Build a small buffer into each variable category. If you budget $400 for groceries, consider it a success if you spend $380. This 5% buffer prevents minor overspending from derailing your entire system.
Seasonal Adjustments
Your zero-based budget should reflect seasonal changes. Summer months might require higher utility costs for air conditioning, while winter months might see increased heating expenses. Review and adjust your budget quarterly to account for these predictable variations.
The 24-Hour Rule
For unplanned purchases over $50, implement a 24-hour waiting period. This simple delay prevents impulse spending that can destroy your carefully planned budget. The Journal of Consumer Research found that implementing purchase delays reduces impulse buying by 31%.
Technology Tools That Enhance Success
Modern budgeting apps have made zero-based budgeting more accessible than ever. YNAB (You Need A Budget) specifically designed their platform around zero-based budgeting principles. Their internal data shows that users reduce debt by an average of $3,000 in their first year.
EveryDollar, created by Dave Ramsey’s team, offers both free and premium versions focused on zero-based budgeting. The premium version connects to your bank accounts for automatic transaction import, reducing the manual work required.
For those preferring spreadsheets, Google Sheets or Excel templates can be equally effective. The key is choosing a system you’ll actually use consistently.
Measuring Success Beyond the Numbers
Zero-based budgeting success isn’t just about staying within spending limits. The real victory lies in the behavioral changes it creates. After implementing zero-based budgeting, most people report:
- Reduced financial stress and anxiety
- Improved confidence in financial decisions
- Better communication about money with family members
- Increased ability to handle unexpected expenses
The American Psychological Association’s 2024 Stress in America report found that people who feel in control of their finances report 40% lower stress levels compared to those who feel financially uncertain.
Making It Sustainable Long-Term
The most successful zero-based budgeters treat it as a evolving system rather than a rigid constraint. Your budget should change as your life changes. A promotion, new family member, or changed living situation all require budget adjustments.
Schedule monthly budget reviews to assess what’s working and what isn’t. This isn’t about judging past performance but about making informed adjustments for the future. According to the Federal Trade Commission’s financial literacy research indicates that people who review their budgets monthly are 60% more likely to achieve their financial goals.
The Bottom Line
Zero-based budgeting works because it forces intentional decision-making about every dollar. It’s not about restriction; it’s about conscious choice. When you decide in advance where your money goes, you eliminate the anxiety of wondering where it went.
The method requires more initial effort than other budgeting approaches, but the payoff is substantial. You’ll develop a deeper understanding of your spending patterns, eliminate wasteful expenses, and make consistent progress toward your financial goals.
Remember that zero-based budgeting is a skill that improves with practice. Your first month won’t be perfect, and that’s completely normal. Focus on the process, not perfection, and you’ll develop a financial management system that serves you for years to come.
The most important step is starting. Choose your budgeting tool, calculate your income, and begin assigning every dollar a purpose. Your financial future depends on the decisions you make today.
Frequently Asked Questions
Q: How long does it take to create a zero-based budget? A: Initially, expect to spend 2-3 hours setting up your first zero-based budget. This includes reviewing bank statements, calculating averages, and setting up your tracking system. Monthly maintenance typically takes 30-45 minutes once you’re familiar with the process.
Q: What if I have irregular income as a freelancer or contractor? A: Use your lowest monthly income from the past six months as your baseline budget. Any income above this amount should be allocated to building a larger emergency fund or paying down debt faster. This conservative approach prevents overspending during lower-income months.
Q: Should I include my spouse’s income in a zero-based budget? A: Yes, if you share financial responsibilities. Successful zero-based budgeting requires both partners to understand and agree on spending categories. Schedule monthly budget meetings to review performance and make adjustments together.
Q: What happens if I overspend in one category? A: You must reduce spending in another category to maintain the zero balance. This might mean eating out less if you overspent on groceries, or skipping a clothing purchase if you exceeded your transportation budget. The key is making conscious trade-offs in real-time.
Q: How much should I budget for emergencies? A: Start with $1,000 as your initial emergency fund goal, then build toward 3-6 months of expenses. Include emergency fund contributions as a line item in your zero-based budget until you reach your target amount.
Q: Can I use zero-based budgeting if I’m paying off debt? A: Absolutely. Zero-based budgeting is particularly effective for debt payoff because it ensures every available dollar goes toward either necessary expenses or debt reduction. List minimum debt payments as fixed expenses, then allocate any remaining money to paying extra on your highest-priority debt.
Q: How often should I update my zero-based budget? A: Create a new budget every month before the month begins. Your income might remain stable, but expenses often vary monthly. Additionally, review and adjust your budget quarterly to account for seasonal changes or life changes.
Q: What if I hate tracking every expense? A: Start by tracking only the variable categories where you tend to overspend. Many people find that tracking just 3-4 problem categories provides most of the benefits without the overwhelm. You can always add more detailed tracking later as the habit develops.
Loading comments...
Leave a Comment(Login required)